Buford Home Buyer's Guide: Budget, Neighborhoods, Offers, and Closing
Buying a home in Buford, GA begins with a realistic payment range, a clear location strategy, and financing preparation before the right property appears. This Buford Home Buyer's Guide walks through the local search process, from setting a sustainable budget to comparing neighborhoods, evaluating homes, and writing an offer you can follow through on. Buyers organize these decisions around the details that matter most: Monthly costs, commute patterns, home condition, and long-term fit.
Buford Real Estate Overview
Buford is a city in Gwinnett County, with a small portion extending into Hall County. Its two main mailing ZIP codes, 30518 and 30519, cover a much larger area than the city limits, including unincorporated Gwinnett neighborhoods.
| Metric | Recent reading |
|---|---|
| Median sale price, Buford area (12 months through September 2026) | About $475,000 |
| Median sale price, 30519 (as of November 2, 2026) | About $509,950, down 2.0% year over year |
| Median sale price, 30518 (as of October 11, 2026) | About $467,500, up 0.9% year over year |
| Active listings (November 2026) | 581, averaging about $727,000 |
| Typical days listed | About 40 |
Conditions can differ substantially by neighborhood, price point, property condition, and seller timeline. Use current listings and recent comparable sales to evaluate an individual home rather than relying on a single area-wide figure.
Buford Home Buyer's Guide: What the Market Looks Like Right Now
Buford is best approached as a selective, property-by-property market rather than a market where every home calls for the same offer strategy. Prices have been roughly flat over the past year, with one ZIP code slightly up and the other slightly down, and supply in both sits near six months. Those figures do not define every Buford neighborhood, but they point to a setting where buyers can benefit from careful comparison and disciplined budgeting.
Well-presented homes that are priced in line with recent comparable sales can still attract quick interest. Homes with dated finishes, deferred exterior work, unusual layouts, restrictive community rules, or less flexible timing may create more room for discussion. The right response is not to assume leverage or competition before reviewing the property itself.
For first-time buyers, the most useful starting point is often a clear distinction between needs and preferences. A lower payment may matter more than an extra bedroom or a particular finish level, and buyers starting around $300,000 will generally be looking at townhomes, condos, or older and smaller detached homes. Move-up buyers may place more weight on functional space, lot usability, storage, commuting routines, and future flexibility.
A focused search also makes it easier to recognize value when it appears. Comparing asking prices, days on market, condition, and seller terms using our Buford market report provides a stronger basis for decisions than reacting to a listing's photos alone.
Is Buford a Buyer's or Seller's Market Right Now?
- Market balance varies by price, condition, location, and the seller's timing.
- Median prices in Buford's two main ZIP codes moved less than 3% in either direction over the past year.
- Supply of roughly six months in both ZIP codes points to a balanced market with some room to negotiate.
- Buyers entering today should be ready to move on well-priced homes while still comparing terms and condition carefully.
Buford Home Buyer's Guide Step 1: Set a Realistic Budget Before You Search
A realistic Buford budget is the monthly cost you can maintain comfortably, not simply the highest loan amount shown on a lender's estimate. Start with gross household income, recurring debt, savings goals, emergency reserves, and the payment that still leaves room for everyday spending and future plans.
Your ownership cost includes principal and interest, property taxes, homeowners insurance, HOA dues where applicable, utilities, maintenance, and moving expenses. Gwinnett County calculates annual property taxes from assessed value, generally 40% of fair market value, multiplied by the applicable millage rate. For 2026, the county's total rate for unincorporated properties is 14.71 mills, held steady for a seventh year. School taxes add 20.15 mills for Gwinnett County Public Schools, and addresses inside Buford city limits carry city and Buford City Schools levies instead, so the total varies by address.
HOA dues are especially important to verify in planned communities because they can change the monthly payment picture even when two homes have similar purchase prices. Insurance should also be quoted for the specific address because coverage, deductibles, construction features, and carrier availability affect the premium.
Run several price and down-payment scenarios before narrowing your search. The mortgage calculator can help you compare payments at different purchase prices and interest rates.
Pre-qualification is an early estimate based largely on information you provide. Pre-approval is a more documented lending review. Genuine affordability goes further by accounting for cash to close, reserves after closing, household expenses, and the financial flexibility you want to keep.
Monthly Cost Breakdown by Price Point in Buford
The examples below assume 20% down, a 30-year fixed rate of 7.18% (the national average reported by Freddie Mac on November 5, 2026), and Gwinnett County's 14.71-mill county rate. Tax estimates exclude exemptions, school levies, city taxes, HOA dues, maintenance, and address-specific insurance.
| Purchase price | Estimated principal & interest | County property tax | Insurance | Total estimated monthly cost |
|---|---|---|---|---|
| $300,000 entry-level | $1,626 | $147 | Quote by property and policy | $1,773 plus insurance, HOA, and maintenance |
| $475,000 near the area median | $2,574 | $233 | Quote by property and policy | $2,807 plus insurance, HOA, and maintenance |
| $650,000 move-up | $3,523 | $319 | Quote by property and policy | $3,842 plus insurance, HOA, and maintenance |
County tax calculations follow Gwinnett County's assessed-value method and 2026 rate. Rates move weekly, so rerun these figures with a current lender quote.
Step 2: Get Pre-Approved Before You Search in Buford
Pre-approval helps a Buford buyer act with more certainty when a suitable home appears. Sellers can more easily evaluate an offer when the buyer has a documented financing range, a lender contact, and a clear understanding of the cash needed to close.
Pre-qualification is usually an initial conversation or estimate based on information supplied by the buyer. Pre-approval typically requires a lender to review income, assets, debts, credit, and supporting records. Gather recent pay stubs, W-2s, tax returns, bank statements, identification, and documentation for large deposits or additional income before you begin touring seriously.
The Consumer Financial Protection Bureau explains that a preapproval letter can show a seller that the lending process has begun, while final approval still depends on the property and full underwriting.
First-time buyers can also ask lenders about Georgia Dream, the state's down-payment assistance program. Program information effective July 8, 2026 lists a maximum sales price of up to $625,000 and standard assistance of up to $10,000, with a larger amount for eligible healthcare workers, educators, public protectors, and military members.
Ask your lender to model several payment scenarios, including different down payments, rate changes, insurance estimates, and HOA dues. A firm spending ceiling makes it easier to compare homes quickly without stretching beyond the payment that fits your priorities.
Step 3: Choose the Right Area of Buford for Your Lifestyle and Budget
The right part of Buford depends on whether your priority is walkability, newer construction, yard space, commute access, or a lower-maintenance routine. Instead of treating Buford as one uniform market, compare the community type and day-to-day lifestyle each location offers.
Downtown Buford can suit buyers who prefer an established setting near local restaurants, shops, and community activity. Housing styles and lot sizes can vary, so buyers should look closely at parking, drainage, renovation quality, and how an older layout works for their household.
The Mall of Georgia area can be a practical choice for buyers who value access to shopping, dining, and major travel routes. Nearby communities often include newer layouts and neighborhood amenities. Traffic patterns at the times you normally travel, HOA rules, and monthly dues deserve as much attention as the home's finishes.
North and northeast Buford include subdivisions and larger-lot settings with homes from different construction eras. These areas can appeal to move-up buyers seeking more bedrooms, flexible work space, outdoor room, or storage. Compare roof age, HVAC service history, grading, drainage, and exterior upkeep when homes vary in age and maintenance level.
School research should remain address-specific. Homes inside Buford city limits are generally served by Buford City Schools, while many homes with a Buford mailing address fall under Gwinnett County Public Schools, and the Hall County portion is served by Hall County Schools. Verify attendance boundaries and enrollment details for each property rather than making an area-wide assumption.
Step 4: Search Strategically and Evaluate Properties
An effective Buford property search begins with criteria tied to your budget and routine. Define your preferred home type, bedroom and bathroom needs, commute boundaries, minimum storage, lot requirements, and non-negotiable features before setting alerts.
Use the Buford homes for sale search to monitor properties that match your criteria, then refine the filters as you learn which compromises are workable. At a first showing, look beyond staging and listing photographs:
- Check natural light, room flow, storage, noise, parking, and driveway access.
- Look for visible moisture, drainage issues, uneven floors, roof wear, and deferred exterior maintenance.
- Review available records for major systems, repairs, permits, and HOA obligations.
- Consider how the layout works for furniture, remote work, guests, hobbies, and future needs.
- Visit surrounding streets at different times when possible.
Older homes may offer established surroundings and character. Newer homes may offer different layouts, systems, and community amenities. The better choice is the one that aligns with your payment comfort, location priorities, and willingness to manage maintenance over time.
Step 5: Make a Competitive Offer in Buford
A competitive Buford offer is one you can complete confidently, not simply the highest number you can offer. Sellers often weigh price alongside financing readiness, earnest money, requested closing date, contingencies, and the clarity of the contract terms.
Begin with comparable homes that match the property's location, age, condition, size, lot, and features. A well-priced home with visible interest may call for a clean offer and a prompt decision. A home that has been available longer, needs updates, or has a difficult seller timeline may create more room to negotiate price, closing-cost contributions, included items, or timing.
Earnest money is a good-faith deposit that is generally credited toward the buyer's funds at closing if the transaction proceeds under the contract. The appropriate amount depends on the home, the negotiated terms, and the obligations you are prepared to take on.
An escalation clause can be useful when competition is clear, but it should set a maximum price you can afford and require evidence of a competing offer. Keep your requested deadlines realistic, and avoid offering terms you do not fully understand. A reliable offer balances a seller's priorities with the protections and timeline you need to move forward responsibly.
Pro-Tip: The most common offer mistake is focusing on price while overlooking the full monthly payment and contract deadlines. Set your payment ceiling and negotiating limits before a favorite home creates pressure.
Step 6: Inspections, Due Diligence, and Closing in Buford
After an offer is accepted, the next phase is about confirming the property, completing lender requirements, coordinating title work, and meeting the dates in your contract. Keep a written calendar for lender requests, property-review deadlines, insurance tasks, and the scheduled closing date.
A general home inspection is common, and additional evaluations may make sense based on the home's age, systems, site conditions, and seller disclosures. Buyers may seek closer review of roofing, pest activity, sewer or septic systems, drainage, HVAC equipment, structural concerns, pools, or other property-specific features.
Georgia buyers should take due diligence seriously. Georgia is generally a "buyer beware" state, and buyers are expected to use ordinary and reasonable care when evaluating a property, so the due diligence period is your main window to investigate.
In Georgia, a closing attorney commonly coordinates title and settlement work. Your lender and closing attorney will provide transaction-specific figures for loan charges, prepaid insurance and taxes, title-related charges, and the funds required to close. Avoid opening new credit accounts, changing employment, or moving large sums of money without discussing the impact with your lender first.
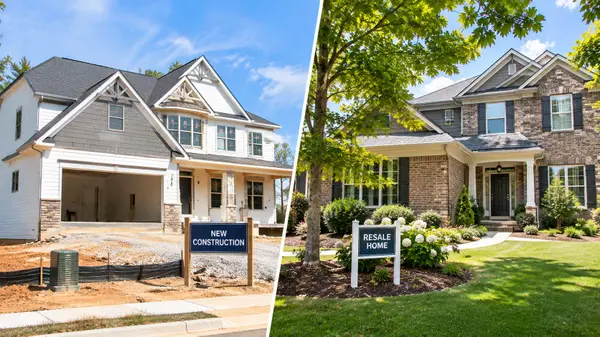
New Construction vs. Resale Homes in Buford
| Consideration | New construction | Resale home |
|---|---|---|
| Price structure | May include base pricing, lot premiums, and selected upgrades | Reflects location, condition, updates, lot characteristics, and seller pricing |
| Negotiability | May center on incentives, upgrades, or closing-cost support | May include price, timing, repairs, or personal-property terms |
| Property review | Independent review can identify items before closing | Maintenance history and current condition require careful review |
| Customization | Design selections may be available before construction milestones | Updates are generally completed after purchase |
| Move-in timeline | Can range from quick move-in to a longer build schedule | Usually follows the negotiated contract timeline |
| Warranty coverage | Builder warranty terms may apply | Coverage depends on transferable warranties, if any |
| Financing | Builder-related financing offers may be available | Buyers can compare lending options based on their needs |
Ready to Buy in Buford?
Billy Little and The Keely Collective, a Century 21 Results team founded by North Atlanta specialist Keely McNeal, work with first-time and move-up buyers across Buford, turning a realistic budget, property priorities, and offer strategy into a clear home-search plan backed by real-time listing alerts. Call or text Billy at (470) 281-7853, email billy@keelycollective.com, or reach the team at (678) 448-8004. You can also tell us what you are looking for.
Frequently Asked Questions: Buying a Home in Buford
How much do I need for a down payment to buy in Buford?
Your down payment depends on the loan program, credit profile, lender requirements, and purchase price. On a $300,000 home, 3% is $9,000, 10% is $30,000, and 20% is $60,000, before planning separately for closing funds and reserves. The CFPB recommends discussing available loan options and cash-to-close requirements with a lender.
How long does it take to buy a home in Buford from search to close?
The timeline varies because the search phase depends on finding a home that fits your budget and priorities. Once under contract, the closing date is set by the agreement, while lending, title work, property reviews, and required documentation shape the path to settlement. Your contract and lender timeline should guide the schedule for your purchase.
Is Buford a good place to buy a home right now?
Buford can be a sensible place to buy when a home's payment, location, condition, and long-term usefulness align with your plans. The area's median sale price was about $475,000 over the 12 months through September 2026, with prices roughly flat year over year, which supports a careful, property-specific approach. Compare each home with similar active and recently sold properties before deciding.
What are closing costs for buyers in Buford?
Buyer closing costs can include lender charges, prepaid insurance and taxes, title-related expenses, and other transaction-specific items. The amount depends on the loan, purchase contract, and property, so request a written estimate from your lender and closing attorney early in the process. This helps you distinguish the down payment from your total cash needed to close.
Do I need a buyer's agent in Buford, and what does it cost?
A buyer's agent can help you compare homes, prepare offers, coordinate deadlines, and understand local transaction steps. Compensation is negotiable and should be discussed clearly before touring, including how any fee may be handled in the transaction. The most important step is understanding the services, obligations, and compensation terms in writing.
Recent Posts