Alpharetta Home Buyer's Guide: A to Z
Buying a home in Alpharetta, GA is one of the biggest financial decisions you will make, and the right approach is highly local. This Alpharetta Home Buyer's Guide begins with the essential answer: set a monthly payment limit that includes taxes, insurance, association fees, and maintenance before you tour. Organize financing, compare property types, evaluate neighborhoods, and prepare clear offer terms. The steps below explain how to create a realistic budget, search with purpose, and move toward closing with confidence.
Alpharetta Real Estate Snapshot
Alpharetta is a city in North Fulton County and a higher-priced market where buyers benefit from evaluating each home against comparable properties, monthly ownership costs, and their own long-term priorities. As of November 2026, the median sales price for Alpharetta is $750,564, while the average sales price sits at $1,111,291. That gap tells you something useful: a smaller number of high-end sales pull the average up, while many buyers are shopping well below it.
First-time buyers should not assume Alpharetta is out of reach. Townhomes, condos, and smaller attached homes can come up in the $300,000s, so a focused search with a firm payment ceiling can still uncover realistic starting points.
Market pace, seller flexibility, and available choices can differ significantly by location, condition, home type, and price tier. Rather than relying on one market-wide headline, compare homes with similar square footage, updates, lot characteristics, and nearby alternatives.
What the Alpharetta Home Buyer's Guide Says About Today's Market
Alpharetta buyers should treat current conditions as property-specific because a home's location, presentation, price, and competing options can create very different negotiating positions. Well-prepared homes in convenient locations often command quick attention, while listings with dated finishes, less functional layouts, or extended market exposure may give buyers more room to compare terms.
The local housing stock includes townhomes, established subdivision homes, newer communities, and larger residences on private lots. A $750,564 median sales price signals why a defined payment ceiling matters before narrowing a search. Buyers should decide early whether commute time, lot size, renovation level, bedroom count, walkability, or lower-maintenance living carries the most weight.
Pricing is also shaped by the condition of competing homes. A recently updated property can command a different response than a similar-sized home needing near-term work. Buyers should compare asking price, likely ownership costs, and resale appeal together instead of treating a new listing as automatically superior or a longer-listed property as automatically discounted enough.
Our Alpharetta market data, including recent sales and days on market, provides a useful starting point for comparing local property types and price ranges. A focused search plan helps buyers respond thoughtfully when a suitable home appears.
Is Alpharetta a Buyer's or Seller's Market Right Now?
Alpharetta is best approached as a home-by-home market, with negotiating leverage shaped by price, condition, location, and competing inventory.
- Properties that are accurately priced, move-in ready, and aligned with buyer preferences may draw faster attention than homes needing updates or carrying less flexible terms.
- Competition can vary between townhomes, established subdivisions, newer construction, and upper-tier homes.
- For a buyer entering today, verified financing, a complete cost estimate, and current comparable-property research create a stronger position than urgency alone.
Step 1: Set a Realistic Budget With This Alpharetta Home Buyer's Guide
A realistic Alpharetta purchase budget starts with the payment you can comfortably sustain, not simply the maximum amount a lender may approve. Begin with gross household income, recurring debt, savings goals, moving costs, cash reserves, and the lifestyle expenses you want to maintain after closing.
Your monthly ownership estimate should include principal, interest, property taxes, homeowners insurance, and applicable homeowner association fees. Georgia generally assesses property at 40% of fair market value, while taxing jurisdictions establish their own millage rates. In October 2026, Fulton County adopted a 2026 general-fund rate of 8.87 mills, holding it steady for the fifth straight year, but it is only one part of a property's possible tax bill. Municipal, school, special-district, and county jurisdiction differences, along with exemptions, can change the final amount. The Georgia Department of Revenue's property-tax guidance explains the assessment framework.
Association dues also deserve a full review. They can support amenities, landscaping, private roads, exterior maintenance, or reserves, but the payment amount and responsibilities vary by community. Ask for the current budget, rules, payment schedule, and any planned assessments.
Pre-qualification is generally an initial estimate based on information supplied by the borrower. Pre-approval involves a more detailed lender review, yet genuine affordability is the payment that still leaves room for savings and unexpected ownership costs. Use a mortgage calculator to test different purchase prices and down-payment scenarios.
Monthly Cost Breakdown by Price Point in Alpharetta
The examples below assume 20% down, a 30-year fixed loan at 7.18% (the national weekly average reported by Freddie Mac on November 5, 2026), and Fulton County's 2026 8.87-mill general-fund levy. This illustration applies only to a property subject to that county levy. Other levies, exemptions, and the property's taxing jurisdiction can change the final tax bill.
| Purchase price | Estimated mortgage payment | Property tax | Insurance | Estimated monthly subtotal before insurance, HOA, and maintenance |
|---|---|---|---|---|
| Starter example, $300,000 | $1,626 | $89 county general-fund baseline | Property-specific quote | $1,715 |
| Entry-level example, $500,000 | $2,710 | $148 county general-fund baseline | Property-specific quote | $2,858 |
| Median-price example, $750,564 | $4,068 | $222 county general-fund baseline | Property-specific quote | $4,290 |
| Move-up example, $1,200,000 | $6,503 | $355 county general-fund baseline | Property-specific quote | $6,858 |
The mortgage illustrations use the stated loan assumptions. County tax estimates use Georgia's 40% assessment framework and Fulton County's 8.87-mill general-fund rate (Fulton County, October 2026). Insurance, HOA dues, maintenance, and additional tax levies require property-specific estimates. Rates move weekly, so rerun these numbers with your lender's current quote.
Step 2: Get Pre-Approved Before You Search in Alpharetta
Pre-approval gives an Alpharetta buyer a clearer search range and a more credible position when it is time to submit an offer. Sellers can see that a lender has reviewed key financial information, which helps distinguish a prepared buyer from someone who has only estimated what they might borrow.
A pre-qualification may rely primarily on information you report, while a pre-approval usually involves more documentation and lender review. Lenders use these labels differently, so ask exactly what has been verified and whether the letter reflects your assets, income, debts, and credit profile.
Prepare recent pay stubs, W-2 forms, tax returns, bank statements, identification, and documentation for your down payment funds. Self-employed buyers, buyers using gift funds, and buyers with recent employment changes may need additional records. The Consumer Financial Protection Bureau's loan application packet checklist outlines common documentation.
Keep your search within the payment range you selected, even if a lender approves a higher amount. That discipline protects room for ownership costs that become clearer once you identify a specific home.
Step 3: Choose the Right Alpharetta Area for Your Lifestyle and Budget
The right Alpharetta area is the one that fits your everyday routine, preferred home type, and payment comfort level. Buyers should compare community types rather than assuming the city offers one uniform experience or one predictable price range.
Downtown and central Alpharetta can suit buyers who prioritize restaurants, parks, events, and a connected daily routine. Housing may include townhomes, established homes, and newer development near amenities. Buyers should compare walkability, parking, lot size, and HOA obligations alongside the home's finish level.
Windward and established amenity communities may appeal to move-up buyers seeking neighborhood recreation features, larger floor plans, and a community setting. These homes can vary widely by renovation level, lot location, and association structure. Review dues, governing documents, and maintenance obligations before making an offer.
Larger-lot and estate-style settings can work well for buyers who value privacy, outdoor space, flexible rooms, or more separation from nearby homes. The tradeoff is often greater responsibility for landscaping, drainage, exterior upkeep, and utility planning. A larger property can have a substantially different long-term cost profile from a similarly priced home on a smaller lot.
Townhome and lower-maintenance options can be practical for first-time buyers, relocating professionals, healthcare workers with long shifts, and households that prefer fewer exterior responsibilities. Shared walls, smaller private outdoor areas, rental restrictions, and detailed association standards are common considerations. Compare the monthly fee with the services and maintenance responsibility it may reduce.
School research should always be tied to the specific property address and a household's needs. Attendance boundaries, programs, transportation, and school information can change, so confirm current details directly before making a location decision.
Step 4: Search Strategically and Evaluate Properties
An effective Alpharetta search begins with firm criteria, timely alerts, and organized tour notes rather than first impressions alone. Start with current homes for sale in Alpharetta, set up real-time listing alerts, then define a clear price ceiling, preferred home type, minimum bedroom count, commute needs, and non-negotiable features.
At each showing, look beyond staging and cosmetic updates:
- Compare the floor plan with how you work, store belongings, host guests, and use outdoor space.
- Check natural light, room dimensions, parking, traffic noise, drainage, and exterior condition.
- Ask about the home's age, major updates, utility setup, association obligations, and maintenance history.
- For older homes, consider the likely remaining life of major systems and whether renovations appear consistent with the rest of the property.
- For newer communities, review nearby construction activity, completion timing, and association documents.
Save photos and notes immediately after each tour. When several homes are viewed in a short period, a simple comparison sheet can help you assess the complete ownership experience rather than only the most memorable kitchen, backyard, or staging detail.
Step 5: Make a Competitive Offer in Alpharetta
A competitive Alpharetta offer aligns with the property's position, the seller's priorities, and your verified financial capacity. Price matters, but a clear timeline, credible financing, and terms you can genuinely meet may also influence the seller's decision.
Start by reviewing comparable homes, listing condition, time on market, and visible competition. Earnest money is negotiated in the contract, so the appropriate amount depends on the price, financing, and complete offer terms. It should demonstrate commitment without exceeding the cash you can reasonably allocate.
Build the offer around a realistic lending timeline and a closing date you can meet. Contract protections should be selected thoughtfully because they allocate meaningful buyer risk. Removing important protections simply to appear aggressive can create financial exposure that outweighs a modest advantage in price or speed.
An escalation clause can be useful when multiple offers are expected, but it needs a defined maximum that fits your payment comfort. Other negotiating levers can include flexibility on possession, prompt lender documentation, and a clean communication process. The strongest offer is one that is prepared, understandable, and sustainable after closing.
Pro-Tip: The most common offer mistake is responding to urgency without comparing the complete monthly cost and contract terms. Avoid it by setting a firm ceiling before negotiations begin.
Step 6: Due Diligence and Closing in Alpharetta
The period after an accepted offer is when buyers confirm property details, complete lender requirements, and prepare for a documented closing. In Georgia, residential closings are generally handled through a Georgia real estate attorney and the attorney's closing team. The Georgia Supreme Court has stated that attorney participation is required in real estate closings involving deeds.
The contract controls the important dates, so review every deadline and responsibility promptly with your real estate, lending, and legal professionals. Depending on the home's age, systems, visible conditions, and intended use, buyers may arrange a general property review and additional specialist evaluations related to roofing, drainage, wood-destroying organisms, pools, chimneys, or sewer lines.
Before closing, review lender documents, confirm required funds, secure insurance, verify final figures, and complete a final walkthrough. The interval between contract and closing depends on the agreement, loan progress, title work, and property-specific conditions. New-construction delivery dates may also shift.
Buyer costs can include lender charges, attorney services, prepaid insurance, prepaid interest, taxes, and transaction-specific fees. Compare the Loan Estimate with the Closing Disclosure and ask about meaningful changes before signing. Your final cash requirement should be clear before the closing appointment.
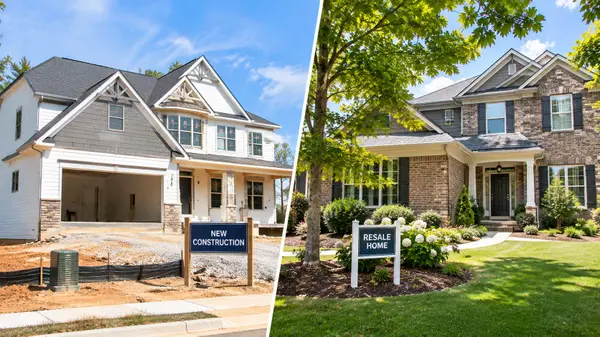
New Construction vs. Resale Homes in Alpharetta
New construction can offer design choices and possible builder incentives, while resale homes make it easier to evaluate an established setting, lot, and maintenance history.
| Consideration | New construction | Resale home |
|---|---|---|
| Typical price premium | Can reflect builder, lot, location, and selected finishes | Can reflect location, condition, updates, and lot characteristics |
| Negotiability | May focus on financing incentives, upgrades, or delivery timing | May focus on price, timing, inclusions, and condition |
| Property review considerations | Independent review can identify incomplete work or defects | Review can clarify age, upkeep, repairs, and system condition |
| Customization options | May allow finish and design selections before completion | Changes are generally made after purchase |
| Move-in timeline | May be immediate or depend on construction completion | Usually follows the negotiated closing date |
| Warranty coverage | Builder and product warranties may apply under their terms | Coverage depends on transferable warranties or negotiated protections |
| Financing differences | Builder-affiliated financing may offer incentives, so compare full loan terms | Buyers can compare lenders based on their preferred financing strategy |
Ready to Buy in Alpharetta?
Whether you are buying your first townhome in the $300,000s or comparing move-up homes near Windward, a clear plan makes every decision easier. Billy Little and Keely McNeal, pair real-time listing alerts with hands-on guidance from people who answer your calls, review comparables with you, and negotiate to protect your budget. Call or text Billy at (470) 281-7853, email billy@keelycollective.com, or reach the team at (678) 448-8004. You can also start a no-pressure conversation here about your payment range, location priorities, and buying timeline.
Frequently Asked Questions: Buying a Home in Alpharetta
How much do I need for a down payment to buy in Alpharetta?
The amount depends on your loan program, lender requirements, and financial profile. In the monthly examples above, a 20% down payment would be $60,000 on a $300,000 purchase or $100,000 on a $500,000 purchase, though many loan programs allow less than 20% down. Buyers should also plan for closing funds, reserves, and property-specific costs.
How long does it take to buy a home in Alpharetta from search to close?
The search timeline depends on your criteria, financing readiness, and the homes available within your price range. Once under contract, the closing date is set by the agreement and depends on loan progress, title work, and property-specific requirements.
Is Alpharetta a good place to buy a home right now?
Alpharetta can be a sound choice when the home, monthly payment, location, and ownership horizon fit your personal plan. With a median sales price of $750,564 as of November 2026, careful comparison and a sustainable payment limit are especially important.
What are closing costs for buyers in Alpharetta?
Buyer closing costs can include lender charges, attorney services, prepaid insurance, taxes, and other transaction-specific fees. Your Loan Estimate and Closing Disclosure should show the final cash needed, so compare both documents before signing.
Do I need a buyer's agent in Alpharetta, and what does it cost?
A buyer's agent can help you compare properties, understand contract terms, coordinate deadlines, and prepare an offer strategy. Compensation and services should be discussed and documented before you proceed, including how the fee will be handled in your transaction.
Recent Posts