Cumming Home Buyer's Guide: Budget, Search, Offer, and Close With Confidence
Buying a home in Cumming, GA works best when you set a sustainable payment limit, secure financing clarity, and compare each property against realistic alternatives. This Cumming Home Buyer's Guide gives first-time and move-up buyers a practical route from budgeting through closing. The most important step is separating a lender's maximum approval from a monthly cost that still supports savings, everyday expenses, and future home maintenance. From there, buyers can evaluate homes, locations, and contract terms with greater confidence.
Cumming Real Estate Snapshot
Cumming is the county seat of Forsyth County, and most homes with a Cumming mailing address sit in unincorporated Forsyth County rather than inside city limits. Recent market readings give useful context for a search.
| Metric | Recent reading |
|---|---|
| Median sale price (12 months through October 2026) | About $610,000, down roughly 2.4% year over year |
| Typical time to go under contract | About 38 days |
| Active listings (November 2026) | 1,125 |
| Average asking price of active listings (November 2026) | $756,000 |
| Typical active listing | About 4 bedrooms and 3,150 square feet |
These figures provide broad context for a Cumming home search, rather than a price expectation or monthly-payment estimate for every available property. Buyers starting around $300,000 will generally be looking at townhomes, smaller or older detached homes, or homes that need some updating.
Cumming Home Buyer's Guide: How to Assess Market Conditions
Cumming market conditions are best evaluated property by property because price, condition, location, and listing history can affect buyer leverage more than a single market label. A well-priced, move-in-ready home can attract quick attention, while a property with extended market time, deferred maintenance, or repeated price changes may create room for discussion around price, timing, or seller-paid costs.
Start with active listings, then compare them with recent sales that match the home's type, age, lot, condition, and location. A newer home in a planned community may draw a different buyer pool than an established home on a larger lot, even if the asking prices appear similar. Days on market can be useful, but the number matters most when viewed beside the home's price history and competing options.
The median sale price of about $610,000 does not define every price point. Buyers may find lower-priced options by adjusting expectations around square footage, home age, location, or renovation needs. Larger homes, recently built properties, and homes with high-end finishes can sit well above that reference point.
The practical question is not whether every listing favors buyers or sellers. It is whether a specific home has credible alternatives, whether its condition supports the asking price, and whether the full payment fits your financial plan. Our Cumming market report, with recent sales, average prices, and days on market, can provide a useful comparison starting point. Look beyond list price to lot usability, community dues, commute patterns, major system age, and likely updates after closing.
Is Cumming a Buyer's or Seller's Market Right Now?
- Market balance can vary by price point, condition, and location within Cumming. Prices have eased slightly over the past year, which can give prepared buyers a bit more room on some listings.
- A listing's days on market, price history, and nearby active alternatives provide more useful negotiating context than a citywide label alone.
- Homes with practical layouts, solid condition, and realistic pricing can draw attention early, while homes with clear tradeoffs may offer more negotiating room.
- For a buyer entering today, preparation matters most: establish a payment ceiling, compare alternatives, and tailor terms to the individual home.
Cumming Home Buyer's Guide Step 1: Set a Realistic Budget Before You Search
A realistic budget is the monthly ownership cost you can maintain comfortably, not the highest purchase price a lender may approve. Begin with gross household income, recurring monthly debt, savings goals, moving expenses, and the cash you want available after closing. A general housing-payment guideline can be a helpful starting point, but your debt-to-income profile, loan type, and personal priorities should determine the final limit.
Include principal and interest, property taxes, homeowners insurance, HOA dues when applicable, utilities, routine upkeep, and a reserve for larger repairs. In Cumming, the exact payment can vary substantially between homes with similar list prices because tax bills, insurance needs, HOA obligations, loan terms, and property characteristics are not identical.
Forsyth County assesses real property at 40% of fair market value before applicable exemptions. County and school millage rates can change from year to year, and each parcel's bill may differ based on exemptions and the applicable tax districts. The county outlines its assessment process, tax calculation, and exemptions on its property tax information page.
Pre-qualification is an early lending estimate based on preliminary information. Pre-approval involves a more detailed review of income, assets, credit, and debts, but neither one automatically establishes genuine affordability. Compare several payment scenarios, including taxes, insurance, HOA dues, and savings goals, before setting a search ceiling. A mortgage calculator makes it easy to test a few price points side by side.
Monthly Cost Breakdown by Price Point in Cumming
The examples below show principal and interest only, using the 7.18% national 30-year fixed average reported by Freddie Mac on November 5, 2026. Property taxes, insurance, HOA dues, and mortgage insurance (when putting less than 20% down) are added on top.
| Purchase price | 10% down: principal & interest | 20% down: principal & interest |
|---|---|---|
| $300,000 | About $1,829 | About $1,626 |
| $450,000 | About $2,744 | About $2,439 |
| $610,000 (near the median) | About $3,719 | About $3,306 |
Monthly ownership costs still depend on the loan terms, down payment, property-tax bill, insurance quote, HOA dues, and the individual property's condition. Compare lender-provided payment scenarios for each serious home and add the actual annual tax bill, insurance quote, and any community dues.
A lower-priced home may reduce principal and interest, but it can still carry meaningful ownership costs if it needs near-term updates or has higher recurring dues. A higher-priced home may have a larger payment but lower immediate repair needs. The useful comparison is the complete monthly and annual cost of each property, not the purchase price alone.
Step 2: Get Pre-Approved Before You Search in Cumming
Pre-approval helps a Cumming buyer act decisively because it clarifies the financing range before the right home appears. Sellers and listing representatives can more easily evaluate an offer that includes a lender letter and complete financing details, especially for appropriately priced homes that may draw early interest.
Pre-qualification is generally based on preliminary financial information. Pre-approval usually includes a lender review of credit, income, assets, and debts, although final approval still depends on the loan file and the property meeting requirements. The Consumer Financial Protection Bureau's pre-approval guidance explains why sellers often expect a pre-approval letter with an offer.
Gather these items before beginning a serious search:
- Recent pay stubs and W-2s, or tax returns for self-employed buyers
- Bank and investment statements
- Government-issued identification
- Documentation for bonuses, gifts, recurring debts, or additional income
- Questions for the lender about cash to close, payment limits, and loan options
First-time buyers can also ask lenders about Georgia Dream, the state's down-payment assistance program, which offers additional assistance to eligible healthcare workers, educators, public protectors, and military members.
Avoid opening new credit accounts or moving large sums without a clear paper trail while the lender is reviewing your file.
Step 3: Choose the Right Area of Cumming for Your Lifestyle and Budget
The right Cumming area matches your daily routine, preferred home style, and long-term cost expectations. Compare communities at different times of day, drive the routes you expect to use, and evaluate individual streets and homes instead of assuming a broad area delivers the same experience throughout.
Downtown and the City Center area can suit buyers who want dining, events, and trail access close by. If that walkable rhythm appeals to you, it is worth reading about living near Cumming City Center and the greenway trails.
Planned-community settings can suit buyers who want a neighborhood-oriented environment, shared amenities, and a more intentional community layout. HOA fees, lot sizes, finish levels, and home ages can vary considerably, so compare each listing's dues, restrictions, amenities, and location within the community. These homes may appeal to buyers who value sidewalks, nearby gathering spaces, and a consistent neighborhood feel.
Lake-oriented and larger-lot properties may appeal to buyers who value outdoor space, privacy, or more distance between homes. Buyers should pay close attention to drainage, driveway access, wooded areas, septic systems, docks, and ongoing maintenance. These settings can also work well for remote workers seeking dedicated workspace and a quieter environment, provided internet options are confirmed for the property.
Established suburban neighborhoods often provide a mix of traditional layouts, varied home ages, and resale options. They can make comparison shopping easier because buyers may find similarly sized homes with different levels of updating. That creates an opportunity to weigh renovation costs against lot size, location, and the home's existing condition.
Newer construction communities can fit buyers looking for current floor plans and fewer immediate renovation projects. Compare builder upgrades, lot placement, community rules, projected taxes, financing options, and completion timing before deciding whether new construction is worth the premium.
School research should remain property-specific and school-specific. Attendance boundaries, enrollment availability, programs, and published performance information can change, so buyers should confirm the assigned school and current details directly with Forsyth County Schools before planning.
Step 4: Search Strategically and Evaluate Properties
An effective Cumming property search uses clear priorities, prompt follow-through, and a consistent way to compare homes beyond their finish selections. Set alerts by price, location, home type, bedroom count, and must-have features, then adjust the search only after identifying the tradeoff you are willing to make.
Use current homes for sale in Cumming alongside a written list of must-haves, preferences, and deal-breakers. That list keeps tours focused while leaving room for a home that meets your essentials in a different style or location than you initially expected.
At each showing, evaluate:
- Lot slope, drainage, driveway access, and outdoor usability
- Apparent condition of the roof, HVAC equipment, windows, and water heater
- Storage, furniture flow, remote-work space, and future household needs
- HOA rules, parking limits, rental restrictions, and recurring dues
- Traffic, noise, and nearby activity at different times of day
Older homes can offer established landscaping and mature locations. Newer homes can provide contemporary layouts and different maintenance expectations. Neither option is automatically the better value. Focus on the home's condition, total ownership cost, and suitability for how you plan to live.
Step 5: Make a Competitive Offer in Cumming
A competitive Cumming offer matches the home's market position while staying within your financial limits. Price matters, but sellers also evaluate financing strength, earnest money, requested concessions, closing timing, and how straightforward the overall contract appears.
Before writing an offer, compare recent sales, active alternatives, listing history, and the seller's preferred timeline. A newly listed home priced in line with credible alternatives may call for clean terms and a fast decision. A listing with longer exposure or visible condition issues may create room to request closing-cost assistance, a flexible closing date, or other concessions.
Earnest money is negotiated in the purchase contract, not set at one universal amount. Choose an amount you understand and can deliver under the agreement's deadlines. Financing and property-condition contingencies can protect buyers when lending requirements or significant repair concerns arise. Keep those terms clear and proportionate to the home and your risk tolerance.
An escalation clause can be useful when there is credible competition, but it should include a firm ceiling and a requirement for evidence of the competing offer. Decide your maximum purchase price and maximum monthly payment before negotiations begin. A strong offer is not one that wins at any cost. It is one that secures the right home on terms you can sustain.
Pro-Tip: The most common offer mistake is focusing only on price while overlooking payment, timing, and contract terms. Set your financial ceiling before writing, then negotiate from that position.
Step 6: Inspections, Due Diligence, and Closing in Cumming
After an offer is accepted, the next stage is confirming the property's condition, financing, and contract details within the deadlines you negotiated. Move quickly because lender requests, property reviews, insurance quotes, and title work often proceed at the same time.
A general home inspection is common, with additional evaluations selected for the home's characteristics. Depending on the property, buyers may consider roof, sewer or septic, chimney, pool, foundation, mold, radon, or wood-destroying-organism evaluations. The goal is to understand condition, maintenance needs, and costs that may follow ownership.
During due diligence, review the title commitment, survey questions, HOA documents, insurance availability, lender disclosures, and repair discussions. Georgia buyers commonly work with a closing attorney during settlement. Confirm each party's document, funding, and recording responsibilities before closing rather than assuming the same process applies to every transaction.
The Consumer Financial Protection Bureau states that closing costs typically range from 2% to 5% of the purchase price, excluding the down payment. Your final amount depends on the loan, home, lender fees, prepaid items, insurance, title services, and negotiated seller credits. Compare the lender's Loan Estimate with the final Closing Disclosure so changes are understood before settlement.
New Construction vs. Resale Homes in Cumming
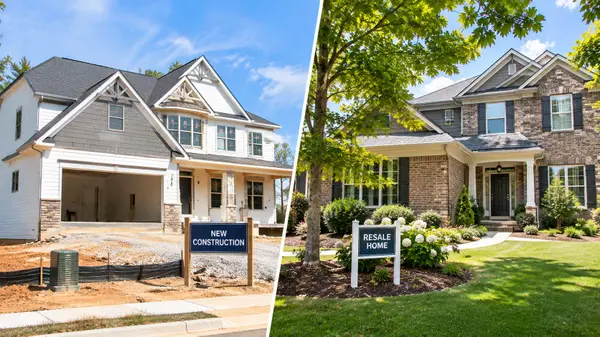
Neither new construction nor resale is automatically better in Cumming: new homes can reduce immediate renovation needs, while resale homes may offer more established locations, lots, and pricing comparisons.
| Consideration | New Construction | Resale Homes |
|---|---|---|
| Typical price premium | May reflect new finishes, upgrades, and community amenities | Varies with age, lot, condition, updates, and location |
| Negotiability | May focus on incentives, upgrades, or closing-cost assistance | May include price, timing, repairs, included items, or concessions |
| Inspection considerations | Independent review can identify incomplete work or installation issues | Review helps clarify maintenance needs, repairs, and system condition |
| Customization options | May allow selections before builder deadlines | Changes happen after purchase and depend on budget and scope |
| Move-in timeline | Could be immediate or depend on construction completion | Usually follows the negotiated closing schedule |
| Warranty coverage | Builder warranty terms and exclusions may apply | Depends on transferable warranties and existing systems |
| Financing differences | Builder-linked incentives should be compared with other loan offers | Buyers can compare Loan Estimates from multiple lenders |
Ready to Buy in Cumming?
Cumming is home base for The Keely Collective, a Century 21 Results team founded by North Atlanta specialist Keely McNeal. Billy Little and the team work with buyers at every price point, from first-time buyers starting around $300,000 to move-up buyers weighing competitive offers, with real-time listing alerts and negotiation focused on protecting your budget. Call or text Billy at (470) 281-7853, email billy@keelycollective.com, or reach the team at (678) 448-8004. You can also reach out here to compare homes, payment scenarios, and offer terms.
Frequently Asked Questions: Buying a Home in Cumming
How much do I need for a down payment to buy in Cumming?
Your down payment depends on the loan program, financial profile, and property you choose. Plan for the down payment plus closing costs, which the Consumer Financial Protection Bureau estimates at 2% to 5% of the purchase price excluding the down payment, as well as moving costs and an emergency reserve.
How long does it take to buy a home in Cumming from search to close?
The search timeline depends on how quickly you find a home that fits your needs and budget. Once under contract, the closing schedule is shaped by financing, property reviews, title work, insurance, and the date negotiated by the parties.
Is Cumming a good place to buy a home right now?
Cumming can be a good fit when a home's payment, location, condition, and lifestyle features align with your priorities. The median sale price was about $610,000 over the 12 months through October 2026, down slightly from a year earlier, but each property should be compared with active alternatives, recent sales, and expected ownership costs.
What are closing costs for buyers in Cumming?
Buyers commonly budget about 2% to 5% of the purchase price for closing costs, separate from the down payment. The final total may include lender charges, title services, prepaid items, insurance, taxes, and negotiated credits, so the Loan Estimate offers the most transaction-specific view.
Do I need a buyer's agent in Cumming, and what does it cost?
A buyer's agent can help compare homes, prepare offers, track contract deadlines, and negotiate terms, although services and compensation should be discussed before touring. Compensation is negotiable, so buyers should request a clear written explanation of services, responsibilities, and any expected costs. If you are still choosing who to work with, this look at choosing a real estate agent in Cumming can help.
Recent Posts